Every FHA and VA loan is assumable. The next buyer can take over your loan at your rate, often hundreds of dollars a month less than a new loan, and that can make your home the one buyers compete for.
15-minute webinar. Presented with an AI-generated likeness and voice of Ken Crotts, created with his consent.
15 minutes. We look at your rate, balance and loan company, and tell you whether your loan is a real selling advantage. No cost, no obligation.
Prefer to pick a time? Book a 15-minute call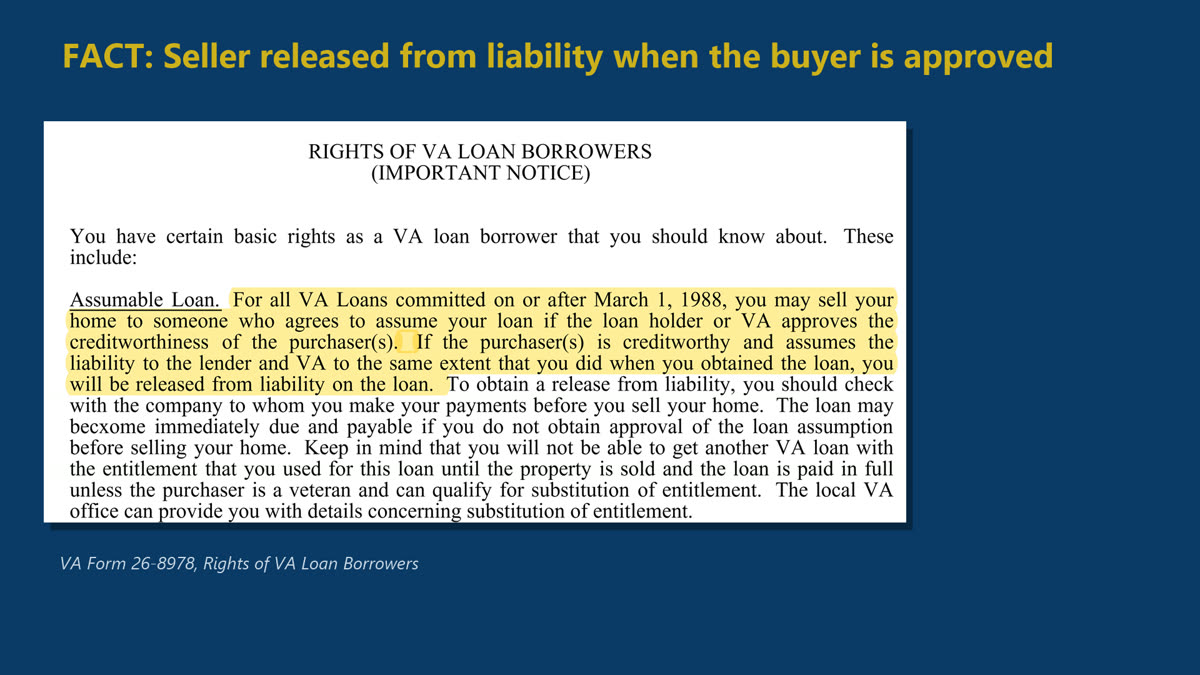
Yes. Any creditworthy buyer approved by the loan holder or VA can assume a VA loan, including a non-veteran (VA Form 26-8978).
Yes. Once the assumption is approved and the buyer takes on the liability, the seller is released (VA Form 26-8978). On FHA loans, the lender approves the buyer and releases the seller on a HUD form.
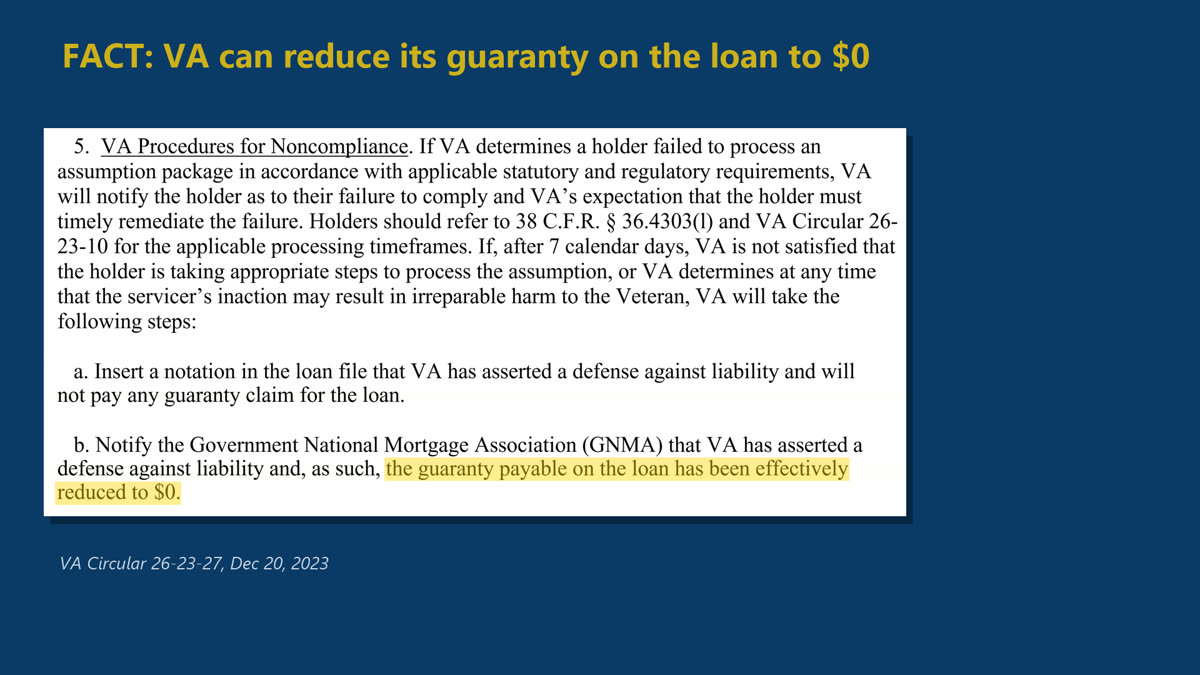
Not if the buyer meets VA's requirements. Under VA Circular 26-23-27 (Dec. 20, 2023), VA can reduce its guaranty on the loan to $0 when a holder fails to comply.
A servicer with automatic authority must decide within 45 days of a complete package; one without it must send the file to VA within 35 days. Our partners see most assumptions close in about 30 to 60 days.
If the buyer is an eligible veteran who substitutes their entitlement, yours is restored. If not, it stays tied to the loan until it is paid off. Selling veterans sign VA Form 26-10291.
Yes. FHA-insured mortgages are assumable when the buyer is approved.
What the loan company can charge is capped by federal rules. The separate assumption service fee is paid by the buyer in our transactions. Current figures are given at your consultation.
Few agents know how to price an assumable home, market it, structure the buyer's cash, protect a veteran's entitlement and hold a loan company to its deadlines, all at once. That's what our team does, with our partners at AssumeList, across Pierce, King and Thurston counties.
We don't push every seller into an assumption. For some homes a traditional sale is better, and we'll show you the numbers for both.
Let's find out. Free 15-minute review, no obligation.
Get my free loan reviewor call or text 206-487-7900